Ownership Economics
Can a Big Island Vacation Rental Pay for Itself?
How to evaluate revenue, expenses, taxes, financing and personal use before buying a Hawaiʻi Island vacation rental
 By Carol Porter, Realtor® · June 15, 2026 Updated: October 4, 2026
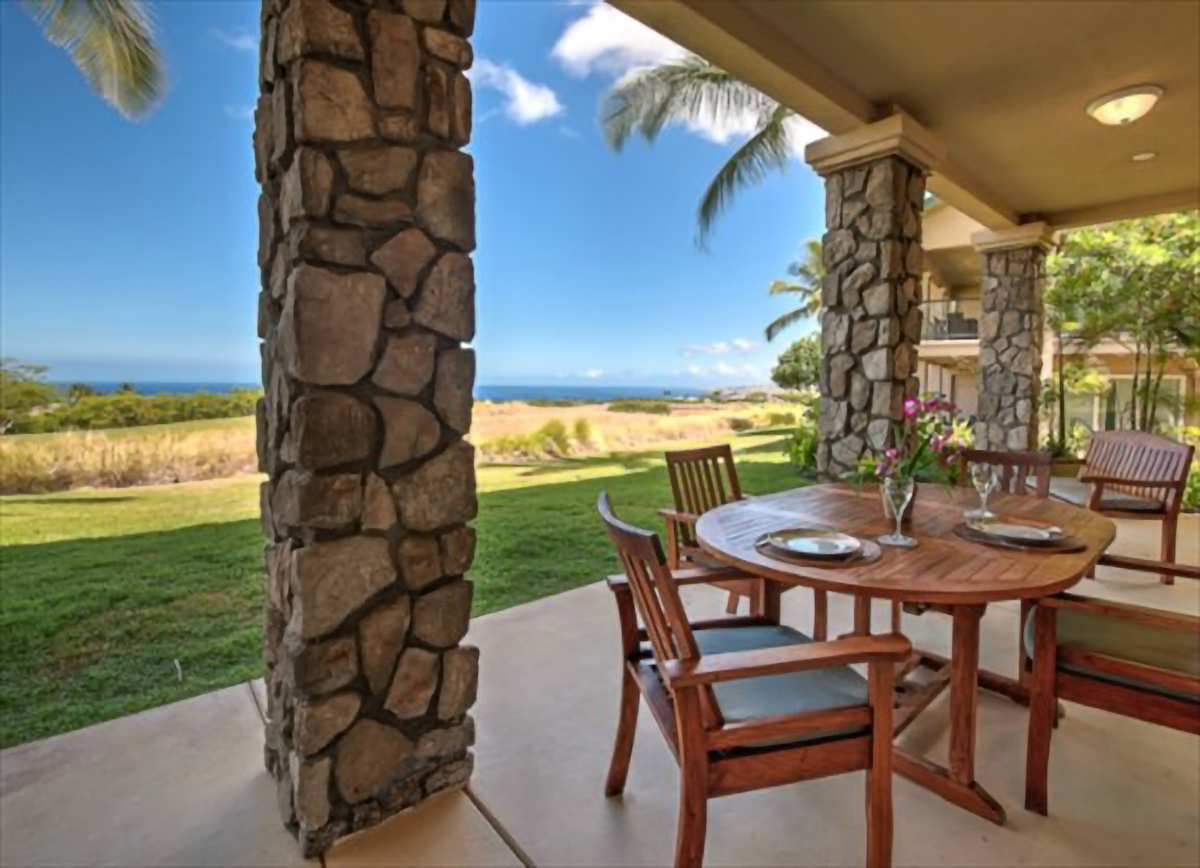
A Hawaiʻi Island vacation rental can generate income that helps cover ownership costs. Whether it covers all of them depends on the particular property, its operating expenses, the buyer’s financing and how much the owner wants to use it personally.
Before deciding whether a property can “pay for itself,” define what that means. Covering association fees, property taxes and other operating expenses is one threshold. Covering mortgage payments and setting aside money for replacements is another. Earning an adequate return on the cash invested is a different question again.
For a buyer considering a Kohala Coast condominium or another Hawaiʻi Island vacation property, I would start with a conservative, property-specific financial projection—a pro forma—rather than a headline about gross rental income.
First, confirm that the intended rental use is legal
For buyers considering a resort condominium or home, Hawaiʻi County's zoning rules provide an important distinction: short-term vacation rentals are permitted in the V (resort-hotel) zoning district. They are also permitted in residential and commercial zoning districts situated within the County's General Plan Resort and Resort Node areas. A qualifying resort property therefore does not necessarily need V zoning to allow STVR use.
This gives resort buyers a defined pathway to vacation-rental ownership, whether the goal is an income-producing property or a second home rented between personal visits. For the particular condominium or home you are considering, confirm its zoning and applicable resort-area designation, complete the required County registration, and review association rules and private covenants for rental restrictions.
Rental eligibility comes before the income calculation. Verify the property’s zoning, applicable approvals, registration status and any conditions affecting the proposed use. A listing’s rental history or a neighboring unit’s advertisements do not establish what a new owner may legally do.
Hawaiʻi County announced that its online Transient Vacation Rental registration platform went live in September 2026. Buyers should use the County’s current guidance to determine the requirements that apply to the specific property, including any transition provisions for existing permitted operations and what is required when ownership changes. See the County’s registration announcement and current Transient Vacation Rental guidance.
County requirements are one layer. Condominium declarations, bylaws, house rules and separate resort or community documents can impose additional restrictions or procedures. For condominiums, identify the Association of Unit Owners, or AOUO, as well as any other association affecting the property.
Confirm the intended rental duration and operating arrangement with the County and review the association documents. Registration or a tax license alone does not settle every question of permitted use.
Gross rental revenue is not owner income
When someone says a unit “grosses $120,000,” ask what is included. Does that figure mean accommodation charges alone, or does it include taxes, cleaning charges and other amounts collected from guests? Is it before or after refunds, platform charges or management fees? Is it a completed year’s actual performance or a projection?
Online booking platforms, such as Airbnb and Vrbo, connect owners or property managers with guests. Their service fees, payment procedures and handling of rental taxes can affect the financial calculation.
Those distinctions can materially change the analysis. A guest’s total payment is not the amount the owner keeps, and a manager’s net payout is not necessarily the property’s net income. The payout may omit expenses the owner pays directly.
A useful projection starts with clearly defined accommodation revenue, then accounts for management, booking costs, operating expenses and any rental-tax cost not recovered through separately collected amounts. That produces an estimate of net operating income. Financing and replacement needs must still be considered before deciding what cash is available to the owner.
The rule is simple: identify every source of income and every expense, and count each once.
Model rental taxes separately
As of October 2026, Hawaiʻi’s State Transient Accommodations Tax is 11%, following the increase effective January 1, 2026. Hawaiʻi County imposes a separate 3% County TAT. Rental activity is also subject to General Excise Tax; for Hawaiʻi County rental activity, the underlying rate is 4% plus a 0.5% county surcharge. The maximum permitted visible GET pass-on rate is 4.712%, which is different from the underlying tax rate.
The State Department of Taxation explains that GET is a tax on the business rather than a conventional sales tax on the customer. Passing it on does not eliminate the business’s filing and payment obligations. See the State’s TAT update, County TAT information, State GET guidance and county-surcharge guidance.
Do not simply deduct a combined percentage from every gross-rental figure. First determine whether that figure includes taxes collected from guests, what receipts are taxable and who collects and remits each tax. If separately collected amounts cover the actual liabilities, they should not inflate the income available to the owner. Any tax cost the owner must absorb still needs to appear in the projection.
A Hawaiʻi tax professional should confirm the treatment of the particular operation, including cleaning charges, how bookings, payments and tax collection are handled through services such as Airbnb or Vrbo and personal use. State and federal income taxes are a separate layer from GET and TAT.
Use the property’s actual ownership expenses
Association fees, property taxes and insurance continue even during a slow rental month. Other expenses change with occupancy, but they do not disappear simply because a manager handles the bookings.
Build the operating budget from current documents and quotes. Include:
- Every AOUO, HOA, resort or community assessment.
- Parcel-specific property taxes.
- Insurance appropriate to the unit and its rental use.
- Electricity and utilities or services not included in association fees.
- Management, booking, platform and payment-processing charges.
- Cleaning and laundry expenses not recovered from guests.
- Repairs, routine maintenance, pest control, supplies and consumables.
- Accounting, licenses, registration and other applicable operating costs.
Verify association inclusions before adding separate expenses. Some communities include water, wastewater, refuse, Internet or cable; others do not. Avoid paying for the same item twice in the model, but do not assume it is included because another development includes it.
Property tax depends on classification and net taxable assessed value, not simply the purchase price. Hawaiʻi County states that short-term rental activity does not qualify for the homeowner tax class. Confirm the parcel’s current classification, any changes associated with the proposed use, and the applicable fiscal-year rates with the County Real Property Tax Office. A seller’s existing bill may not represent the buyer’s future bill.
For condominium insurance, review both the association’s master policy and the coverage the individual owner needs. Ask about deductibles, rental-use exclusions and loss-assessment coverage rather than comparing premiums alone.
Understand what a management fee buys
Professional management can include marketing, pricing, reservations, guest communication, housekeeping coordination, maintenance scheduling and responses to problems. The scope varies by contract, as does the basis on which fees are calculated.
Ask what percentage or fixed fee applies, which receipts it applies to, what services are included and which charges are additional. Platform fees, maintenance markups, linen programs, inspections or onboarding may be separate. Two contracts with the same headline percentage can produce different owner results.
Self-management changes who does the work. It still requires a plan for guest needs, cleaning, repairs, emergencies and applicable local-contact requirements. Include the cost of reliable local support and recognize the time you will spend managing the operation.
Use actual contract proposals in a purchase analysis. A generic management percentage is useful for an illustration, but it is not a substitute for a quote.
Market averages provide context, not a property forecast
Nightly rates and occupancy vary by season, location, unit size, view, condition, amenities, rental restrictions and management. Island-wide averages combine properties that may bear little resemblance to the condominium you are considering.
The official Hawaiʻi vacation-rental performance reports provide dated market context. Their average daily rates and occupancy measures should not automatically become the assumptions used to evaluate a particular purchase.
When available, request multiple years of monthly rental statements, booking records, owner-use calendars and expense records. Compare them with genuinely similar units in the same development. Reconcile revenue to the statements rather than relying solely on a marketing summary.
Also ask how occupancy is calculated. Occupancy measured against nights offered for rent is different from occupancy measured against every calendar night. A unit with substantial owner use can show a strong occupancy percentage while generating less annual revenue.
Your own vacations affect the revenue model
A second home used by its owner is not available to guests every day of the year. Remove personal-use dates and expected maintenance closures from the rental calendar before estimating revenue.
The timing matters as well as the number of nights. If your preferred visits coincide with periods of stronger demand, those stays can displace more potential revenue than the same number of nights in a slower period. That does not make personal use a poor decision; it may be the principal reason for buying. It does mean that your actual plans belong in the projection.
For each month, estimate the nights genuinely available to rent, the proportion likely to be booked and the average accommodation rate on booked nights. Available nights multiplied by booked-night occupancy and average daily rate gives an initial revenue estimate. Allow for cancellations, refunds and discounts, and make sure the occupancy assumption has not already deducted owner use.
Separate property performance from financing
Net operating income, or NOI, measures revenue after operating expenses and before financing. For the framework used here, it excludes depreciation, owner income taxes and unit capital expenditures or replacement funding. Full association dues are included as an operating expense to the owner, even when the association allocates part of those dues to its own reserves.
After estimating NOI, subtract annual debt service—the principal and interest payments on the loan—to estimate cash flow before unit replacement funding and owner income taxes. If a mortgage payment also includes escrow for taxes or insurance, do not deduct those expenses again when they are already included in the operating budget.
Two buyers can purchase the same property and have different cash-flow results because they finance it differently. Paying cash removes debt service, but it does not remove operating costs or the need to evaluate the return on the capital invested.
For an investment comparison, an indicated capitalization rate is annual NOI divided by purchase price. Financing is excluded because cap rate evaluates the property’s operating income relative to its price. It does not capture every part of the investment, including acquisition costs, initial renovations, future capital spending, resale costs or the personal value of using the property. State the NOI convention used when comparing figures.
An illustrative calculation: the same property, different financing
The following figures are invented solely to demonstrate the calculation. They are not Hawaiʻi market averages, a rental forecast or a lending quote.
Assume annual accommodation revenue of $120,000, after refunds and excluding separately collected taxes. For simplicity, guest cleaning charges and matching cleaning costs are excluded from both sides; any unrecovered cleaning cost belongs in operating expenses. Assume guest tax collections are reconciled separately and cover the actual GET and TAT liabilities. If they do not, subtract the shortfall.
Scroll to see the full table
| Annual item | Hypothetical amount |
|---|---|
| Accommodation revenue | $120,000 |
| Management at an assumed 30% of accommodation revenue | −$36,000 |
| All other operating expenses | −$42,000 |
| Net operating income | $42,000 |
| Assumed unit replacement funding | −$6,000 |
| Amount remaining before debt service and owner income taxes | $36,000 |
The $42,000 operating-expense assumption includes association dues, property taxes, insurance, utilities, booking costs not included in management and the other operating expenses described above. It is a placeholder for a complete property-specific budget. The $6,000 replacement allowance is separate from association reserve contributions already included in dues.
Buyer paying cash
With no debt service, this model leaves $36,000 after the assumed unit replacement funding, before owner income taxes. That is a cash-budget result, not proof of an attractive investment return. Assessing return requires the purchase price, acquisition and setup costs, capital invested and future expenditures.
Buyer with financing
If annual principal and interest payments are assumed to be $54,000, the same model produces a cash shortfall of $18,000 after replacement funding and before owner income taxes. The operating property has not changed; the financing has changed the owner’s result.
A lower-revenue year
If accommodation revenue falls 20% to $96,000 and management remains 30%, management falls to $28,800. Holding the other assumptions constant, NOI falls to $25,200. After $6,000 of replacement funding, the cash buyer has $19,200 remaining; the financed buyer with $54,000 debt service has a $34,800 shortfall.
Some operating expenses would also change with occupancy, so this is a simplified sensitivity test. Its purpose is to show why a projection should include a weaker year and a plan to fund the resulting shortfall.
Keep operating liquidity and replacement funding separate
An operating reserve provides cash for uneven revenue, unexpected repairs and bills due before rental proceeds arrive. Establishing that cash buffer is different from recording an annual operating expense; avoid counting both a reserve deposit and the expenses it later pays as separate costs of the same event.
Replacement funding addresses longer-term needs: furniture, appliances, air-conditioning equipment, flooring, paint and other unit components. A rental may also need periodic updates to remain competitive even when its furnishings still function. Set the allowance from the unit’s condition and a replacement schedule, rather than choosing a percentage merely because it makes the result look comfortable.
The association’s reserves address components it is responsible for. They do not necessarily fund replacements inside the unit. Review the reserve study, financial statements, meeting minutes, planned projects and special assessments alongside your own unit budget. The principles in “Is That HOA Fee Really High? How to Evaluate Hawaiʻi Resort Fees” apply here as well: understand what the fee buys, what remains your responsibility and what future obligations are being funded. The Hawaiʻi Real Estate Commission’s condominium resources provide further guidance.
Look beyond one year’s cash flow
A full ownership decision includes costs that an annual rental statement may not show: closing costs, initial furnishings, renovations, future major work and eventual selling expenses. Positive annual cash flow does not automatically mean an adequate total return.
Mortgage principal payments can build equity, but they still require cash. Potential appreciation is a separate assumption, not operating income and not a guaranteed outcome. Neither principal repayment nor hoped-for appreciation pays this month’s bills.
If the property only appears workable after assuming substantial appreciation, higher future nightly rates or unusually strong occupancy, I would revisit the assumptions before treating it as a financially sustainable purchase.
What I would want before relying on a projection
Before using projected rental income to support a purchase, I would want:
- Verification of the intended rental use and the approvals, registrations and ownership-change requirements that apply.
- Association documents, current fees, financial statements, reserve information and planned or outstanding assessments.
- Historical monthly revenue and expense records, with owner use and unavailable dates identified.
- Relevant comparable rental performance and an explanation of each forecast assumption.
- A management proposal identifying its fee basis, included services and additional charges.
- Parcel-specific property-tax information and insurance quotes appropriate to the intended use.
- The buyer’s actual financing terms, acquisition costs and initial setup budget.
- An owner-use calendar, unit replacement plan and sufficient cash for a weaker year.
Then I would compare a base case with a downside case. Test lower revenue, higher association dues or insurance costs, an unexpected repair and time out of service. A projection is more useful when it shows what you may need to contribute than when it merely produces an appealing annual income figure.
So, can it pay for itself?
Sometimes. The answer depends on what expenses you expect the rental to cover and whether the property-specific evidence supports that expectation.
Some buyers want a rental investment that produces cash after operating costs, financing and replacement needs. Others want a second home whose rental income offsets part of the expense of owning a place they enjoy. Both are understandable objectives, but they require different standards for evaluating the purchase.
I would separate the financial projection from the personal value of ownership, then consider both. A home you love can still require an annual cash contribution, and an impressive gross-rental figure can still leave the owner with a shortfall.
The useful question is: After realistic expenses, financing, replacement needs and my own visits, what will this property require from me—and am I comfortable with that commitment?
With aloha,
Carol Porter
REALTOR® · RS-87584 · HI · Better Homes and Gardens Real Estate Island Lifestyle
Related resort guides: Mauna Kea Resort, Mauna Lani Resort, Waikoloa Beach Resort
Next step
Questions about your own search?
Every situation is different, and the details change the answer. Tell me what you’re considering and I’ll give you an honest read.